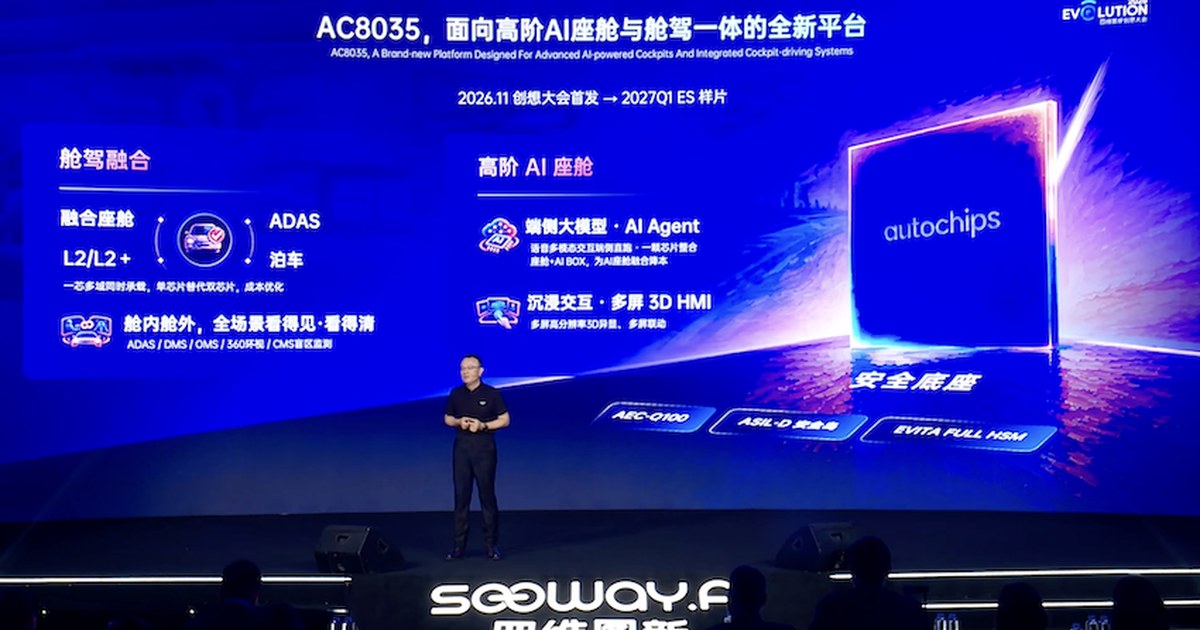
Cost-down cabin + ADAS fusion SoCs are how Chinese OEMs keep smart features on volume cars and ship compliance stacks abroad. The question overseas auto suppliers and domain engineers keep asking is narrower: can one die replace separate cockpit and ADAS controllers, with enough memory bandwidth for cabin agents, without blowing the BOM on mid-tier SKUs? AutoChips’ AC8035 pitch at EVOLUTION is aimed squarely at that cost-and-integration ledger.
What AC8035 is supposed to carry
Per CheDongXi and 财闻 / Sina finance reprints from the same day, AC8035 is framed as a 舱驾融合 (cabin–driving fusion) domain platform: one chip for smart cockpit, L2 / L2+ assisted driving, automatic parking, and 端侧大模型 (on-device LLM) workloads*. NavInfo CEO 程鹏 (Cheng Peng) said the part supports cabin–driving fusion / 舱模一体, claims compute leadership at the same price band*, and says memory bandwidth is about 2–3× prior same-tier designs* so the cabin can stay always-on multimodal without a wake word*. Engineering samples are planned for 2027 Q1* — the stage slide itself showed “2026.11 创想大会首发 → 2027Q1 ES 样片.” Safety messaging on the deck lists AEC-Q100, an ASIL-D safety island*, and EVITA Full HSM* as the base; treat those as vendor claims until datasheets and certifications land.
The same keynote also showed the AC7870 functional-safety series — Cheng said that line already has about 20,000 units shipped* and nine customers*, aimed at safety-class / chassis-adjacent control rather than the AC8035 fusion SoC story. Keep the two SKUs separate when you read the press.
OEM / Tier-1 design-in path — not Digi-Key, not a hobbyist eval board you order tonight. Start at autochips.com (杰发科技) and NavInfo’s EVOLUTION materials. Contacts on the AutoChips site include [email protected] (商务) and [email protected] (技术)*. AC8035 is still pre-sample (ES targeted Q1’27*), so expect NDA roadmaps, reference domain controllers, and long automotive qualification — not a Raspberry Pi–style board drop. Sibling cockpit SoCs already in volume (AC8015 / AC8025 family) are the practical place to study AutoChips’ software baseline, display/ADAS I/O habits, and export-oriented packaging while you wait for 8035 silicon.
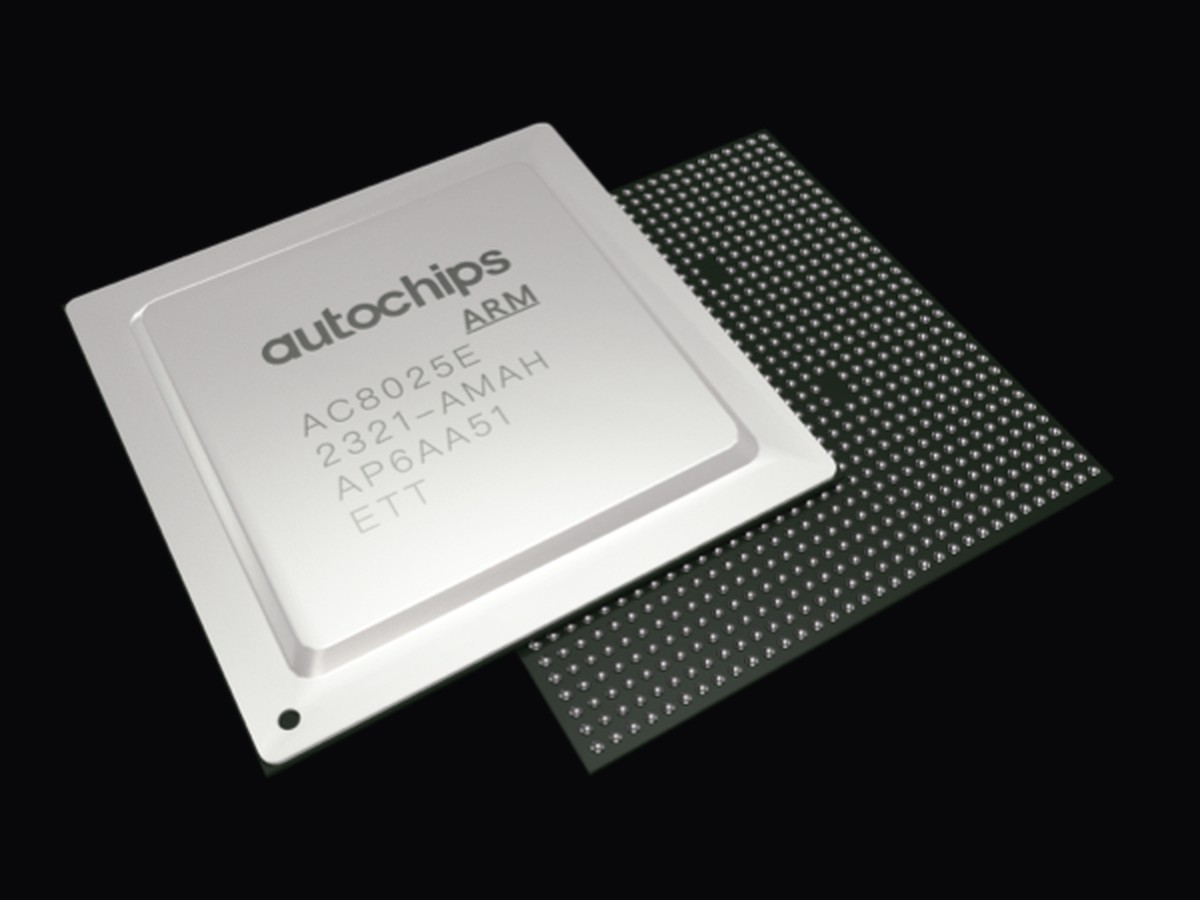
Real official product still from autochips.com AC8025 product page — AutoChips AC8025E cabin SoC package (top + BGA). Used here as related AutoChips cabin-domain visual style; not an AC8035 die shot (8035 product page / package photo not published at launch).
Why the bandwidth and BOM story matters
Cheng’s media follow-up (财闻) put the fusion die in a cost frame: as assisted driving moves into mass-market cars, OEMs care less about peak TOPS posters and more about whether you can cut a separate ADAS box, shrink harness and memory, and still leave headroom for cabin agents that keep evolving after SOP. He said the new generation over-provisions memory bandwidth because car SoC cycles are long while models iterate fast*. NavInfo also claimed that chip + OS + software co-optimization has halved memory demand on some projects*, and that storage-chip inflation pushed them to stretch wafer / DRAM prep from ~3 months to 6–12 months*. Those are supplier talking points — useful as a design intent signal, not as your BOM calculator.
For overseas readers watching Chinese export EVs, the channel claim sits next to the silicon: management said overall overseas revenue is still a small share of the company, but SoC overseas revenue is already >50%*, and safety-domain MCUs have won global top-OEM orders with production planned next year*. Separately, CheDongXi quotes Cheng on AutoChips / NavInfo MCU cumulative shipments >150 million* (今年出货接近 5000 万*), while 财闻 cites SoC cumulative shipments >100 million*. Those are different product lines — MCU vs SoC — so do not collapse them into one “100M chips” headline; keep the asterisks and the category labels.
What changes (and what does not)
- Single-die cabin + L2/L2+ + parking + on-device LLM* — the integration bet vs separate cockpit + ADAS controllers; ES still Q1’27*.
- Memory bandwidth ~2–3× same-tier* — vendor claim aimed at always-on cabin agents / multimodal; await datasheet numbers.
- Compute “leading at same price band”* — marketing; no public TOPS/NPU figure in day-one Chinese press we used.
- AC7870 safety series* — adjacent MCU/safety story (~20k shipped*, 9 customers*); not the AC8035 fusion SoC.
- SoC overseas revenue >50%* — channel signal for export cockpits; company-level overseas mix still low*.
- Shipment base* — MCU >1.5亿* (CheDongXi/Cheng) vs SoC >1亿* (财闻) — attribute carefully; both vendor.
- Not a drop-in for Mobileye / Qualcomm / NVIDIA DRIVE stacks — different ecosystem, middleware, and safety case; expect AutoChips reference software + NavInfo maps/data/compliance glue.
Bottom line: if you have been tracking Chinese cabin SoCs mainly as IVI cost-down parts, AC8035 is the clearer “one box for cockpit agents + L2/L2+ + park” signal from AutoChips this week — with Q1’27 samples*, bandwidth headroom claims*, and an already-exporting SoC channel*. Keep every bench and shipment figure asterisked, ask for the real memory map and safety decomposition under your OEM case, and remember a keynote slide is not a production AEC certificate.